So what? Sometimes you just have to do a post about the toilet. Remember our awesome shag carpet toilet from back when we bought the house?
The toilet was promptly de-shagged after we moved in but for quite some time it still sported a very old-people padded toilet seat. How much more awesome does it get?
Recently we finally sprung for a $7 Bemis molded wood toilet seat from Home Depot. Hey big spender. So here you go: shiny, clean, and much less creepy.
Of course, our toilet overhaul couldn't end there. The throne is rather old and we were feeling like we were literally flushing money down the toilet with each tip of the handle. So we decided to invest another $20 into the pot for a HydroRight Dual-Flush kit, also from Home Depot.
The kit installed really easily despite the slightly less-than-thorough directions. We set both the low flush and the high flush settings to use the least possible amount of water and so far so good. Fancy.
When we went to put the lid back on the toilet, we made a little discovery about just how old our toilet really is. Check out the stamp on the underside of the lid:
The previous owners must have installed it right after they moved in. But it's still chugging [kind of a gross image - sorry], so we'll stick with it for now. Especially now that it's a little bit friendlier to the earth.
Wednesday, August 24, 2011
Tuesday, August 23, 2011
Late Summer Harvest
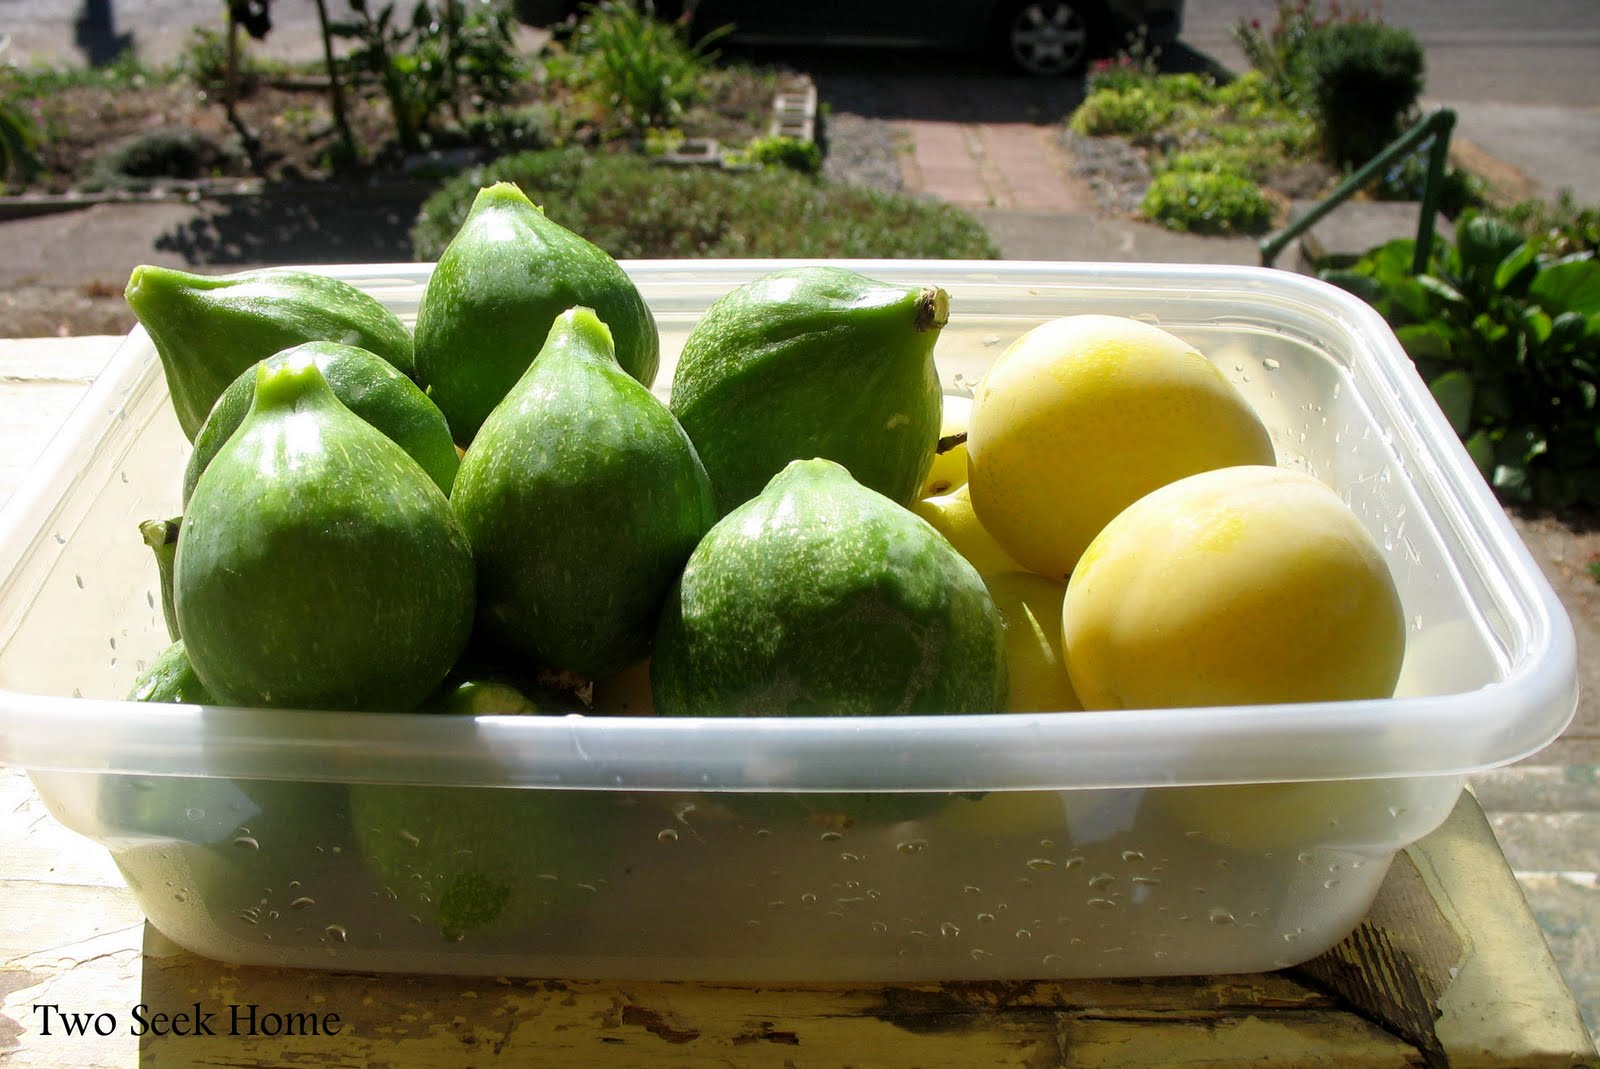
Recently our plums and figs have started to ripen! Our regular purple plums came and went a few weeks ago but these golden plums are just perfect right now. And they are absolutely delicious.
The figs just ripened up out of nowhere in the last couple weeks, too. We'd never eaten figs fresh off the tree and actually had to do a little bit of research.
It turns out that figs can be eaten whole, skins and all, but they are a little bit tricky. Primarily, the sap of the fig tree is apparently a proteolytic enzyme, which destroys proteins in human skin. When figs are not fully ripe they ooze a milky white sap from the tip when picked. If it touches your skin it can irritate or even burn. When eaten, the sap in the skin can make your mouth itchy, numb or sore. The effects are reduced the riper the fig is. We have also been cutting our figs into smaller pieces to reduce the contact our lips and mouth have with the skin. While we've fortunately not experienced it first hand, we've heard that spiders and ants will climb inside the fig as well so cutting it up is a good way to check for critters. Another fun fact: Figs are not a fruit, but a infructescence, which is basically a cluster of flowers.
Here is our harvest from just one day last week:
Bonus: our neighbor doesn't like figs but she loves those golden plums so we were lucky enough to be able to trade for some fresh eggs from her chickens! They made a delicious breakfast this weekend.
Thursday, August 18, 2011
A Little Budget Update
We've had money on the mind for the last week or so. Dawn and Jeremy of Bungalowcious recently disclosed their whopping $257,000 renovation bill for their 1914 bungalow here in Portland (see what they spent it on here). Their house is in a great neighborhood very close to where we looked at some houses in our hunt and if we're not careful we could easily end up in the same position: owners of an incredibly beautiful old house that isn't worth the money we put into it.
We'll get into our thoughts on a reasonable overall budget for our fixer-upper soon, but for now we wanted to share an update to our original budget post since our finances have shifted around a bit since we bought the house.
Remember our original goal for how our finances would look after buying the house?
So how did we do? We've adjusted some of our categories and taken a different approach to tracking our general spending, but as a whole we are actually fairly close to our goal budget. Here's the budget breakdown we've been working with for the last two months:
The important thing, of course, is that our housing expenses are right on track. This category actually includes our mortgage and all the things bundled in with it (hazard insurance, mortgage insurance, taxes) as well as all of our utilities (electric, gas, water and trash). The standard expectation for housing expenses is usually something like 35%, but considering we are at the bottom of our income potential we feel pretty comfortable with 42% for now. We took out the "debt payoff" category because obviously a very large percentage of our income is going to debt payoff on our house alone. We have no credit card debt, so our student loans have the highest interest rate of all that we owe. For now we are putting about 5% of our income toward paying off our student loans, and as we reach a more comfortable level of savings we plan to increase those payments. When we bought the house, almost our entire savings went to the down-payment and initial costs of the house (mostly the sewer replacement and our new washer and dryer). Ever since, we have been putting as much as possible into our accounts to try to get back up to a reasonable emergency fund (we're shooting for a year's worth of mortgage and bills). As we get closer to that goal we'll probably cut back to saving about 10% of our income. The other bills category covers monthly expenses outside of our housing. It includes cable, internet, netflix, our cellphones and our car payment.
In the interest of full disclosure, 14% has not been fully covering all of our spending. What we insist that it covers is our day to day expenses (food, entertainment, gas, etc). We also try to make it cover smaller home improvement needs like paint and screws. Large purchases have to come, at least in part, out of our savings because 14% of our income simply won't cover them. For example, you may (or may not) have noticed that car insurance was not covered in any of the categories above. This is because, to save money, we pay our premium in full every six months. While the total is less than it would be if we were paying it monthly, it is a bit of money to come up with all at once when you're on such a tight budget. Recently we've also taken money for plane tickets back east for Christmas and reservations for our upcoming anniversary weekend out of savings. These types of expenses are only occasional and amount to far less than what we've been putting into savings on a regular basis.
We also have a separate savings account to pay for home improvements. For now we are not contributing to it regularly, but if we have any extra money lying around (for example the nice check we got back from our deposit to our apartment building) it goes into that account to pay for any large purchases for the house.
So here's the thing. It has been pretty much exactly two months since we bought our house and the above was our budget during that time. The way that we have been saving so much has been that my (Caroline here) entire paycheck and a portion of Matt's has been deposited directly into our savings account so that we would never have the opportunity to spend it. Yesterday, however, was my last day at work. So goodbye to my paycheck. Additionally, our health insurance was through my job. So now that it will have to be through Matt's his paycheck is going to be considerably smaller. So goodbye to the portion of his check that was going into savings. So what does that leave going into our savings account? Nada. Zilch. Zero big ones. Especially if we hope to ever get anything done on the house (and probably even if we don't) there is really no way that we can see to spend less than what we have been spending (we're also losing our free coffee and occasionally free food from Starbucks so add that to our expenses). I'll be starting a new (modestly paying) job at the end of September, but in the meantime, with our severely reduced income, this is about what our budget is going to look like:
No savings there. Since we can't do anything about our housing bills (other than doing our best to reduce our use of resources, which we will) our housing will be a whopping 58% of our income! Ouch. We figure since we can't spend much less day to day than we already are we'll just have to do our best for now to keep our savings as low as possible and try not to take much out of savings over the next few weeks.
Beginning in October I'll be receiving a stipend for a Graduate Assistantship from Portland State University. It won't be as much as I was making at Starbucks, but it's something. Of course, once again it will all be going straight into savings. Considering Matt's income will still be reduced due to health insurance, here's what we estimate our budget will look like at that point:
Not bad for two full time students. Speaking of which, since we will both be in school in the fall, all of our student loans will be deferred. It is tempting to put some extra money into the house or to hurry up and pay off the rest of our car just to have one less bill coming in, but we have to remember that our student loans are our highest interest debt. For as long as we have them we'll keep paying the minimum payments on our mortgage and car and put as much money into the student loans as possible. Our graduate loans are the first priority since they are more than a full percentage point higher than my undergraduate loans.
In December Matt will finish his Master's Program and (finger's crossed) should get some sort of a raise at work. At that point everything will change once again. Once we get that savings account up to a good emergency cushion we'll be able to readjust and consider putting more into the house or saving for other things we want to do (vacations!). But for now it's just lots of creative ways to save around here. Maybe there will have to be a post on that soon!
By the way, did you catch that I'm going to be unemployed for the next six weeks!? I'll be spending that time doing lots of work around here so there will be lots of posts to come!! - Caroline
Monday, August 8, 2011
A Closet Story
This weekend we started working on the closet in the room that we plan to use as our bedroom. The closet is full of dark paneling that makes it very dark and ugly:
Isn't it just a great view (and don't you just love the lime green painted wallpaper)?
So far we haven't done much more than a little planning and some demolition (we'll be sure to post pictures when it's done) but in the process we made a little discovery.
The closet in this bedroom backs up to the closet in the front bedroom and we knew that there was not a plaster wall between them but that in some places, that least, the paneling was the only separation. With a closer look, however, we discovered that a lot of the wall is in fact plaster and that it is really only a relatively small section of the wall that is not. Around the same time we noticed that one of the door frames to the closet (see above photo) didn't seem to be of the same quality as the other. With a closer look we could tell that the entire door frame is actually a complete replica! Then we went and checked out the other closet and discovered (we're not sure how we didn't notice before) that the entire wall that the closet is in is actually drywall - not plaster. We started pulling off the wallpaper in the back of the front bedroom closet (yes you read that right) and sure enough the old door frame to the original closet was still there.
What all that means is that these two bedrooms each originally had a small closet which were positioned side-by-side. The previous owners combined the two closets to make one large closet for the back bedroom and decreased the size of the front bedroom to create a new full-size closet for that bedroom as well. Here are some images we drew up using Sweet Home 3D:
The two north bedrooms originally:
The two north bedrooms now:
Closet view in the back bedroom originally:
Closet view in the back bedroom now (same as the second picture at the top of the post):
The closet view in the front bedroom originally:
Closet view in the front bedroom now (you can see how much smaller the room is with the added closet space):
While we're very interested in restoring the house to its original state, the extra closet space is a really big bonus for us and for resale value. These are the only two full size closets in the house, so to restore these closets to their original state would be to remove a huge portion of our main level storage space (outside of the attic and basement). So the plan is to just go ahead with our closet update and keep everything as is. Although we do plan to at some point improve both of the door frames that the previous owners added so that they look like they were always there.
On that note, today we contacted a specialist in old house renovation who recently moved to Portland! She works on old homes alongside owners to help them restore the house to its original glory. We are meeting with her soon to see if she can help us with some of our bigger, more daunting projects. We'll keep you posted!
Friday, August 5, 2011
Love List and Pinterest
We just created a Pinterest account! If you don't know, Pinterest.com is a site that allows you to gather images from anywhere online all in one place. This is really helpful for any kind of interest that requires inspiration. It would have been really helpful when we were planning our wedding but it will be great for compiling inspiration for our home. We're just starting it up but you can check out what we've gathered so far at www.pinterest.com/twoseekhome.
One of the boards that we started on Pinterest is our Love List. This is a collection of products and items that we love from various sources. It is not an advertisement or endorsement for anything, just a little bit of inspiration. Some of them are things we might actually purchase, some are things we wish we could afford and some are just things we really really like. We wanted to share some things that we've added to our Love List so far. Hope you find them as beautiful and inspiring as we do!
Check out our entire Love List and watch for new things we love here: www.pinterest.com/twoseekhome/love-list
One of the boards that we started on Pinterest is our Love List. This is a collection of products and items that we love from various sources. It is not an advertisement or endorsement for anything, just a little bit of inspiration. Some of them are things we might actually purchase, some are things we wish we could afford and some are just things we really really like. We wanted to share some things that we've added to our Love List so far. Hope you find them as beautiful and inspiring as we do!
| Scott Lifshutz watercolor Pillow from West Elm |
![]() |
| Locally made reclaimed Fissure Table from EcoPDX |
Swiss Family Robinson Coasters from Coasting Along
![]() |
| Bungalow Fan by Casablanca Fan Company |
| Shallow Left Center Print by Don Hamerman at 20X200 |
Check out our entire Love List and watch for new things we love here: www.pinterest.com/twoseekhome/love-list
Thursday, August 4, 2011
Kitchen Colors
As of now our kitchen still looks something like this:
No paint yet. But we've been thinking about colors so that when we're ready to paint we'll have an idea of what we're going with. Remember our post on Purple In The Kitchen? Well sure enough, here's the pallet we're settled on for right now:
What do you think? Here's the palette from Behr, including a color that approximately matches those (grimy old) counter tiles:
The white, "moon rise" will be the cabinet color, but we're not quite sure about the other colors. The kitchen is divided into two sections, the main area and a sort of nook area that leads to the basement door. We were thinking about doing the main section in "delicious berry" and the other area in the "gray timber wolf." Behr.com has a tool that allows you to upload a picture and paint the walls to get an idea of what different colors would look like. Here's what we did to the photo at the top of this post:
So what if we switched the colors? Well, it would look something like this:
Not great images, but it gives you the idea. So which do you like better?
Tuesday, August 2, 2011
The History of our House: Somewhere to Start
Our house is really old. Almost as old as Portland itself. See this 1897 map of North Portland?
Here's where our house is:
Or rather, that's where it would be built a mere 13 years later. But more on the history of Portland and our neighborhood another time. We have been researching the history of our house.
The couple that we bought our house told us that our house was built in 1910 by a lawyer living in Portland. Supposedly the house was a kit, shipped from the east coast around the horn of South America. As of yet we don't know who this lawyer is, how long he lived in the house, or most interestingly to us, what company made the kit for our house (Sears-Roebuck is the famous choice, but there were many others). Finding the answers to these questions is going to take a lot of research, and this weekend we got started.
The only definite information we had to start with was the names of the former owners of the house who we know lived here for about 60 years, and a record of the permit for an oil burner from 1945 which has the name of the owner at that time. With a little snooping we were able to find some more information about the former owners of our house.
We were able to find a lot of information in our local newspaper, the Oregonian's historical archives. We paid $9.95 for a day pass to use it, but we were pretty successful. The archives us text recognition to find what you are searching for, and it is amazingly pretty accurate. Just by searching the name of the former owner and our address we were able to find announcements such as the 1967 marriage of one of the couple's daughters:
And earlier, the 1953 birth of their youngest child:
We also came across this interesting tidbit:
We knew that the family before us had lived here for about 60 years, and sure enough there were no records of them being here before 1953. By searching the name, however, we were able to find the announcements of the rest of their children in 1949, 1947 and 1942 at two former addresses:
So we know the former owners moved into this house sometime between 1949 and 1953 (confirming that they lived here for about sixty years), so who lived here before that? We found a record of the permit application for the house's old Oil Burner on portlandmaps.com, an information site run by the city. Lucky for us, the permit is from 1945 and lists the name of the owner at that time:
Since the work was being done for Faye Stanton, seemingly a female head of household, the question was what happened to Mr. Stanton? The next logical step was a free trial membership on ancestry.com. We searched for a Faye Stanton in Portland and sure enough one came up in the 1930 census. It showed her as the wife of Paul B. Stanton. The problem was, it also showed their place of residence as Broadway Ave, not our address:
Back to the Oregonian archives a search for Paul B. Stanton confirmed that Paul B. Stanton had in fact moved to our house at some point after 1930 and had died in 1939, explaining why his wife's name appeared on the Oil Burner permit application:
We also happened to find that the Stanton's had bought the house on Broadway in 1927 for $6500. What a price!
This is where our search hit a wall. We now know that there was at least one more owner before the Stanton's and presumably the previous owner was the original owner. It seems, however, that at some point before the 1930's, the street numbers on our street changed. This makes things a little more complicated.
We searched for our street name in newspapers from 1908-1910 in hopes of finding a record of the building permit. We found two permits for houses that could describe our location at approximately the right time:
Another search on ancestry.com shows that in 1910 William E. Curnow and Jefferson Crandall were in fact neighbors. The street numbers listed on the census form are quite different than ours, despite that they both seem to be on our block.
Additionally, neither Curnow or Crandall are listed as lawyers. If the former owners were right that our house was built by a lawyer, then it seems that neither of these were the original owners of our house.
The 1910 and 1920 census forms however, don't seem to show any lawyers living on our street. So it seems possible that the oral history of our house has been skewed and that one of these listings actually is our house. The next step will really need to be to determine the former addresses of our house and go from there. At some point we plan to take a trip downtown to the Central Library and to the Oregon Historical Society and see what kind of information we can dig up. At any rate, there will be lots more information to come!
Here's where our house is:
Or rather, that's where it would be built a mere 13 years later. But more on the history of Portland and our neighborhood another time. We have been researching the history of our house.
The couple that we bought our house told us that our house was built in 1910 by a lawyer living in Portland. Supposedly the house was a kit, shipped from the east coast around the horn of South America. As of yet we don't know who this lawyer is, how long he lived in the house, or most interestingly to us, what company made the kit for our house (Sears-Roebuck is the famous choice, but there were many others). Finding the answers to these questions is going to take a lot of research, and this weekend we got started.
The only definite information we had to start with was the names of the former owners of the house who we know lived here for about 60 years, and a record of the permit for an oil burner from 1945 which has the name of the owner at that time. With a little snooping we were able to find some more information about the former owners of our house.
We were able to find a lot of information in our local newspaper, the Oregonian's historical archives. We paid $9.95 for a day pass to use it, but we were pretty successful. The archives us text recognition to find what you are searching for, and it is amazingly pretty accurate. Just by searching the name of the former owner and our address we were able to find announcements such as the 1967 marriage of one of the couple's daughters:
![]() | |
| June 6, 1967 |
And earlier, the 1953 birth of their youngest child:
![]() | |
| May 13, 1953 |
We also came across this interesting tidbit:
![]() |
| July 9, 1960 |
![]() | |
| March 19, 1949 |
![]() | |
| February 12, 1947 |
![]() | |
| November 13, 1942 |
So we know the former owners moved into this house sometime between 1949 and 1953 (confirming that they lived here for about sixty years), so who lived here before that? We found a record of the permit application for the house's old Oil Burner on portlandmaps.com, an information site run by the city. Lucky for us, the permit is from 1945 and lists the name of the owner at that time:
Since the work was being done for Faye Stanton, seemingly a female head of household, the question was what happened to Mr. Stanton? The next logical step was a free trial membership on ancestry.com. We searched for a Faye Stanton in Portland and sure enough one came up in the 1930 census. It showed her as the wife of Paul B. Stanton. The problem was, it also showed their place of residence as Broadway Ave, not our address:
![]() | |
| 1930 Census |
Back to the Oregonian archives a search for Paul B. Stanton confirmed that Paul B. Stanton had in fact moved to our house at some point after 1930 and had died in 1939, explaining why his wife's name appeared on the Oil Burner permit application:
![]() | |
| May 12, 1939 |
We also happened to find that the Stanton's had bought the house on Broadway in 1927 for $6500. What a price!
![]() | ||
| June 26, 1927 |
We searched for our street name in newspapers from 1908-1910 in hopes of finding a record of the building permit. We found two permits for houses that could describe our location at approximately the right time:
![]() | |
| April 3, 1910 |
| June 27, 1909 |
![]() | |
| 1910 Census |
The 1910 and 1920 census forms however, don't seem to show any lawyers living on our street. So it seems possible that the oral history of our house has been skewed and that one of these listings actually is our house. The next step will really need to be to determine the former addresses of our house and go from there. At some point we plan to take a trip downtown to the Central Library and to the Oregon Historical Society and see what kind of information we can dig up. At any rate, there will be lots more information to come!
Subscribe to:
Posts (Atom)